Debt Advisory Careers: Roles, Deals and Interview Tips
Key Takeaways
Debt Advisory helps companies and other borrowers structure, evaluate, and negotiate debt financing with lenders.
The role combines financial modeling, credit analysis, lender processes, and negotiation, which distinguishes it from M&A, Leveraged Finance, and Restructuring.
A career in Debt Advisory requires both strong technical finance knowledge and communication and negotiation skills.
Companies typically have borrowing needs regardless of economic conditions. In high-growth markets, businesses may seek capital to expand, fund acquisitions, or execute major capital projects. Then during economic downturns, some companies may be forced to renegotiate debt terms just to keep operating.
Instead of approaching lenders directly, borrowers tend to engage debt advisors for expert and independent advice aligned with their situation, needs, and long-term goals. Debt advisors provide access to a wider network of lenders, run competitive processes to secure superior terms, and mitigate financing risks by managing complex negotiations. That's the kind of work around which debt advisory careers are built.
Read on to learn what the day-to-day work looks like in debt advisory, how the role differs from leveraged finance and M&A, and what you need to know to ace interviews in the space.
Debt advisory is an independent financial service focused on guiding borrowers through the end-to-end lifecycle of raising, structuring, evaluating, and negotiating debt financing. Since debt advisors typically do not lend their own capital, their primary objective is aligned with the borrower. That is, protecting client interests and securing the most favorable borrowing terms available in the market.
The primary debt advisory services include:
Sourcing New Funding: Identifying the most appropriate financing options and lenders based on the borrower's needs and goals.
Refinancing & Capital Optimization: Replacing existing loans or short-term obligations with longer-term or more cost-effective financing structures.
Negotiation Support: Acting as an independent expert to secure competitive interest rates, flexible terms, and favorable covenants.
You'll mostly find dedicated debt advisory teams across several types of financial firms. These include independent investment banks and elite boutiques, accounting and advisory firms like the Big Four, and specialist debt boutiques such as Lincoln International and Clearwater Corporate Finance.
Land your top job in consulting!
Join the world's leading case interview community today and get everything you need to prepare for your upcoming case interviews!
If you join a debt advisory team as an analyst or associate, your work will typically revolve around the primary services outlined above. But the day-to-day workflow is broken down into different tasks based on the deal execution phase.
Debt Capacity Analysis & Financial Modeling
Before reaching out to potential lenders, debt advisory teams analyze the client's historical financial statements, cash flows, and working capital requirements. Then they build financial models to stress-test the company under various economic conditions and estimate debt service capacity.
It's also common for debt advisors to apply credit rating methodologies, similar to those used by Moody's and S&P, to evaluate the company's credit risk profile and determine viable financing thresholds.
Preparing Marketing/Pitch Materials
Once the debt capacity and structure is established, you draft the primary documents required to present the transaction to potential lenders. Your main deliverable is the Confidential Information Memorandum (CIM) — a detailed document laying out the company's business model, historical and projected financials, credit metrics, and proposed financing terms.
Running a Competitive Lender Process
With the pitch materials ready, debt advisory teams reach out to a broad network of traditional and non-traditional lenders, including commercial banks, credit funds, large family offices, and institutional investors. Lenders respond with formal proposals called term sheets. As the lenders submit their term sheets, you'll build a comparison matrix to analyze them across several factors, such as:
Leverage: Total debt allowed relative to earnings, typically expressed as Debt/EBITDA (short for Earnings Before Interest, Taxes, Depreciation, and Amortization)
Pricing: Interest rates, typically based on a benchmark rate plus a margin.
Covenants: Financial and operational rules the borrower must maintain.
Fees: Upfront arrangement fees charged by the lender.
From there, you help the client negotiate, building the supporting analysis and arguments needed to push lenders toward better terms.
Legal Documentation & Closing
After selecting the winning lender, you work closely with legal counsel to draft and review the formal credit agreement. Following industry documentation frameworks set by bodies like the Loan Market Association (LMA) or the Loan Syndications and Trading Association (LSTA), you ensure everything — including legal definitions such as allowed debt baskets, restrictions on payments, and operational flexibilities — matches the commercial agreement.
How Debt Advisory Differs From M&A, Leveraged Finance, & Restructuring
While Debt Advisory (DA), Leveraged Finance (LevFin), and Mergers & Acquisitions (M&A) teams might work together on the same transaction, their responsibilities, perspectives, and alignment are fundamentally different. Rather than joining a deal alongside them, restructuring (RX) tends to take over from the DA when the client's debt situation shifts.
Debt Advisory vs. M&A
M&A teams focus on business valuation, target acquisition strategy, and purchase price negotiations. Debt advisory teams focus on how that purchase price will be financed without placing operational strain on the target's post-closing cash flows.
Debt Advisory vs. Leveraged Finance
LevFin teams typically work inside underwriting banks that put their own money at risk, and get paid through underwriting fees baked into that loan. Their job is to write credit memos, win approval from their bank's credit committee (the internal group that signs off on how much risk the bank is willing to underwrite), and sell the debt to the market without taking on excessive underwriting risk.
On the other hand, debt advisory teams sit on the borrower's side, negotiating against LevFin groups to secure maximum flexibility and lower pricing for the borrower.
Debt Advisory vs. Restructuring
Debt advisory and restructuring share a lot of technical fundamentals. Both require fluency in credit, covenants, and capital structure. But they diverge on the client's capital needs, who the advisor represents, and what winning looks like. At most major firms, standard debt advisory groups generally focus on the financing needs of solvent borrowers looking to raise or optimize capital.
If a company enters severe debt distress, operational underperformance, or insolvency, the work typically shifts to restructuring and liability management. So, restructuring advisors generally step in once a company can no longer service its debt as originally agreed. Debtor-side advisors work for the distressed company, negotiating with creditors to extend maturities, cut leverage, or avoid a formal filing. Creditor-side advisors represent lenders or bondholders instead, protecting recovery value when a borrower is in distress.
Feature
Debt Advisory (DA)
Leveraged Finance (LevFin)
Mergers & Acquisitions (M&A)
Restructuring (RX)
Primary Client
The borrower (company or PE sponsor)
The lending bank / underwriter
The buyer or seller of a business
The distressed company (debtor-side) or its creditors (creditor-side)
Balance Sheet Risk
None. Does not lend money
High. Commits bank capital to underwrite loans
None. Advises on transaction value
None. Does not lend money
Core Technical Focus
Debt capacity, terms, and covenant flexibility
Credit committee approval and loan distribution (syndication)
Business valuation (DCF, comps) and deal structuring
Debtor/creditor negotiation, plans of reorganization, and liability management
Compensation
Advisory retainers and success fees
Arrangement fees and underwriting spreads
Success fees based on deal size
Advisory retainers and restructuring/completion fees
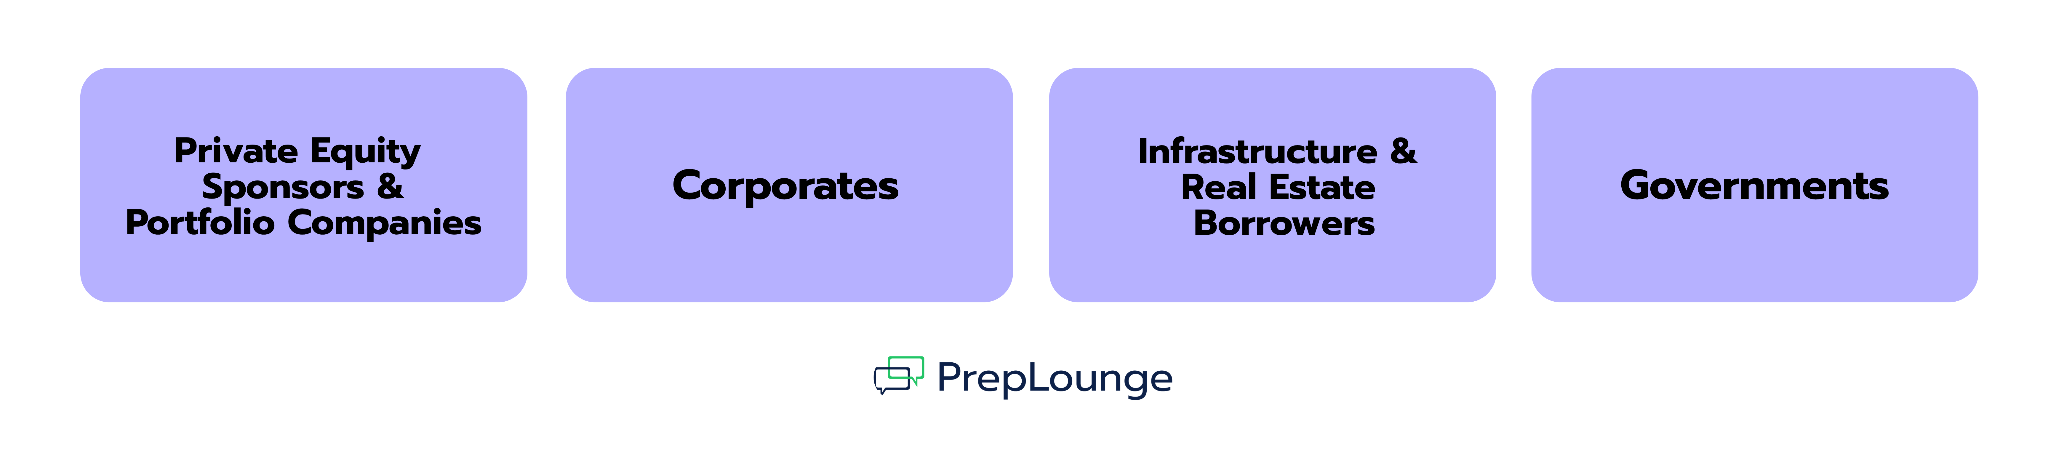
Typical Clients and Deal Situations for Debt Advisory
Debt advisory groups advise different borrower types, each with its own recurring deal types.
Private Equity Sponsors and their Portfolio Companies
Financial sponsors are a major source of dealflow for debt advisory groups. They hire debt advisors to maximize investment returns while protecting their equity risk. Common deal scenarios include:
Acquisition/Leveraged Buyout (LBO) Financing: Arranging the debt package that funds a buyout, usually running in parallel with the M&A negotiation itself, through a competitive multi-lender process aimed at high leverage, low margins, and minimal covenant restrictions.
Add-On Acquisition Financing: Sourcing additional credit facilities so an existing portfolio company can fund a bolt-on acquisition of a smaller competitor.
Dividend Recapitalizations: Raising new debt against a mature, cash-generative portfolio company so the sponsor can pay itself an early dividend without selling the business.
Refinancing Existing Buyout Debt: Replacing debt taken on at the original purchase once market rates or credit conditions shift.
Corporates
Regular operating businesses, from mid-sized manufacturers to large public firms, engage debt advisors to manage liquidity, optimize their balance sheet, and navigate changing credit markets. Common deal scenarios include:
Maturity Refinancing: Extending repayment deadlines and updating old loan terms well before existing loans or bonds come due.
Growth Capital & Project Financing: Raising debt to fund major capital expenditures, geographic expansion, or new manufacturing facilities without diluting shareholder equity.
Private Placements: Raising debt directly and quietly from institutional investors, mainly insurance companies, instead of going through the public bond market.
Infrastructure and Real Estate Borrowers
Deal scenarios for this category of clients include project financing for long-lived physical assets like toll roads or power plants, where the debt is repaid from the specific project's future cash flows. Another example is real estate development financing, secured against a specific property rather than a company's overall balance sheet.
Governments
Unlike corporate debt advisory, Sovereign Debt Advisory deals exclusively with nation-states rather than corporations. Since sovereign nations cannot be liquidated in a corporate court, these deals operate under international law and geopolitical frameworks. So in some firms, this can be a different practice area or a specialist team within the financing division.
Deal scenarios include sourcing new external financing, such as sovereign bond issuances, and managing existing domestic and external debt loads through refinancing.
Once a sovereign's debt becomes unsustainable rather than just costly, the work crosses into sovereign debt restructuring. Recent, real-world examples include Sri Lanka, Zambia, and Ghana, each of which worked through major sovereign debt restructurings with the help of independent advisors.
Skills Needed for Debt Advisory Roles
If you’re interested in debt advisory thus far and want to excel in the field, you’ll need a balance of quantitative skills and clear commercial communication.
Technical Skills
At the foundation, you need real fluency in accounting, finance, and valuation methods. Beyond that baseline, three areas of capital structure knowledge come up in nearly every deal:
Financial Modeling & Waterfalls: Understanding how cash flows through a financial statement to pay down senior debt first, followed by junior debt, before any remaining cash goes to equity holders.
Credit & Covenant Literacy: Understanding of core credit metrics including Total Debt/EBITDA (total leverage relative to earnings), Interest Coverage or EBITDA/Interest (a company's ability to cover its interest payments from earnings), and the Debt Service Coverage Ratio (DSCR — total cash flow available divided by total debt payments due, a measure of how comfortably a borrower can meet its obligations).
Understanding Legal Covenants: Knowing the difference between Maintenance Covenants (financial metrics tested regularly, like quarterly leverage limits) and Incurrence Covenants (rules triggered only when taking specific actions, like issuing additional debt).
Soft Skills
Soft skills in debt advisory are just as important as the technical side. Sometimes you may be negotiating simultaneously with multiple creditor groups that each have competing interests and need to be brought into agreement.
You need genuine negotiation skill, discretion given the confidential nature of a client's financial information, and the ability to build long-term relationships with a relatively small, repeat universe of lenders and investors. Clear writing and presentation matter too, since a big part of the job is producing materials that convince lenders or rating agencies to say yes.
How to Prepare for Debt Advisory Interviews
Interviews for entry-level advisory roles and lateral roles typically focus on testing your understanding of capital structure mechanics, transaction nuances, and market conditions. Here are a few prep tips to help you.
Practice with Common Technical Questions
We’ve mentioned earlier that technical skills are required to excel in debt advisory. After mastering the accounting, valuation, and capital structure foundations, look for the common interview questions in debt advisory interviews and practice answering them out loud. A few examples include:
Walk me through a debt service waterfall.
Walk me through how debt seniority works
What is the difference between maintenance and incurrence covenants?
If interest rates rise by 2%, how does that impact a borrower's debt capacity?
What is the difference between direct lending and syndicated loans?
How are leverage ratios like debt relative to cash flow used to assess risk?
Know Current Market Conditions
Stating specific, current macro data points in your answers is one of the easiest ways to signal genuine market awareness in an interview. Look up numbers that match the team you're talking to. If you're talking to a group focused on healthy corporate advisory or private equity sponsors, know recent figures on buyout deal volume, private credit market growth or yields, and capital raising trends.
To give strong interview answers, don’t just state a number but connect it to a "so what." For example, a strong answer doesn't just say "private credit market assets under management have kept climbing." Instead, it continues with what that means for the desk you're interviewing with: "...which typically means borrowers have a credible alternative to bank financing, giving debt advisors more leverage to negotiate better pricing and looser covenants when running a competitive lender process." The number alone shows you read the news but connecting it to the deal implications shows you understand the business.
Research the Specific Firm's Actual Track Record
Research your target firm overall, then the specific division you're interviewing for. Aim to have specific details on the division including real numbers. For instance, Rothschild & Co has done 1700+ financing and restructuring deals in the past five years. Citing a specific, correctly-framed number like this immediately demonstrates real firm- and group-specific preparation.
Conclusion
Debt advisory plays an essential role in corporate finance by giving borrowers an independent, expert voice during crucial capital raises and refinancings. Debt advisors operate across every economic cycle — funding growth in boom times and helping companies optimize their balance sheets in downturns — which is part of why many in the industry consider it one of the more resilient and technically rewarding career paths in investment banking.
Whichever client type you end up working with, sponsors, corporates, real estate clients, or governments, the underlying job is the same: understand exactly how much a borrower can safely take on, then go get them the best possible terms for it. Success in the field requires both technical fluency in credit and capital structure mechanics, and strong negotiation and relationship-building skills.
Common Questions About Debt Advisory and Related Careers
Debt Advisory teams analyze debt capacity, structure financing, and compare proposals from different lenders. They also support clients during negotiations and help manage the process through closing.
M&A primarily focuses on valuation and transactions, while Debt Advisory focuses on financing structures and borrowing terms. Leveraged Finance teams typically sit within banks that arrange debt financing and may take on underwriting risk.
Typical clients include private equity sponsors and their portfolio companies, corporates, and infrastructure and real estate borrowers. Governments may also receive advice through specialized Sovereign Debt Advisory teams.
Key technical skills include financial modeling, credit metrics, capital structures, and covenant analysis. Strong negotiation, communication, and relationship-building skills are also important.
Candidates should be comfortable with technical topics such as debt seniority, covenants, debt capacity, and different financing structures. They should also follow current credit market developments and research the specific firm and team they are interviewing with.
Sources and Research Behind This Article
To ensure this article is accurate and useful, we reviewed trusted industry sources, official company information and relevant PrepLounge expertise.